Mortgage rates Doom & Gloom got you down? History says to cheer up!
 Engel & Völkers Tampa Downtown · Market Commentary
Seven Percent Is Not the Problem You Think It Is
A look at where mortgage rates actually sit in fifty-five years of history, why the last few years taught us the wrong lesson, and what the same math looks like two hours north.
AARON BOND · BROKER, ENGEL & VÖLKERS TAMPA DOWNTOWN · 2026 FLORIDA REALTORS DIRECTOR, DISTRICT 6
Last week the 30-year fixed mortgage crossed 7% for the first time this year. Freddie Mac's survey put it at 7.03% for the week ending September 24 — up from 6.95% the week before, and 73 basis points higher than a year ago. The Federal Reserve had raised its benchmark rate on September 16, its first increase since 2023.
I've had a version of the same conversation every day since. Some variation of: we missed it.
I want to make an argument against that, and I want to make it with numbers rather than optimism.
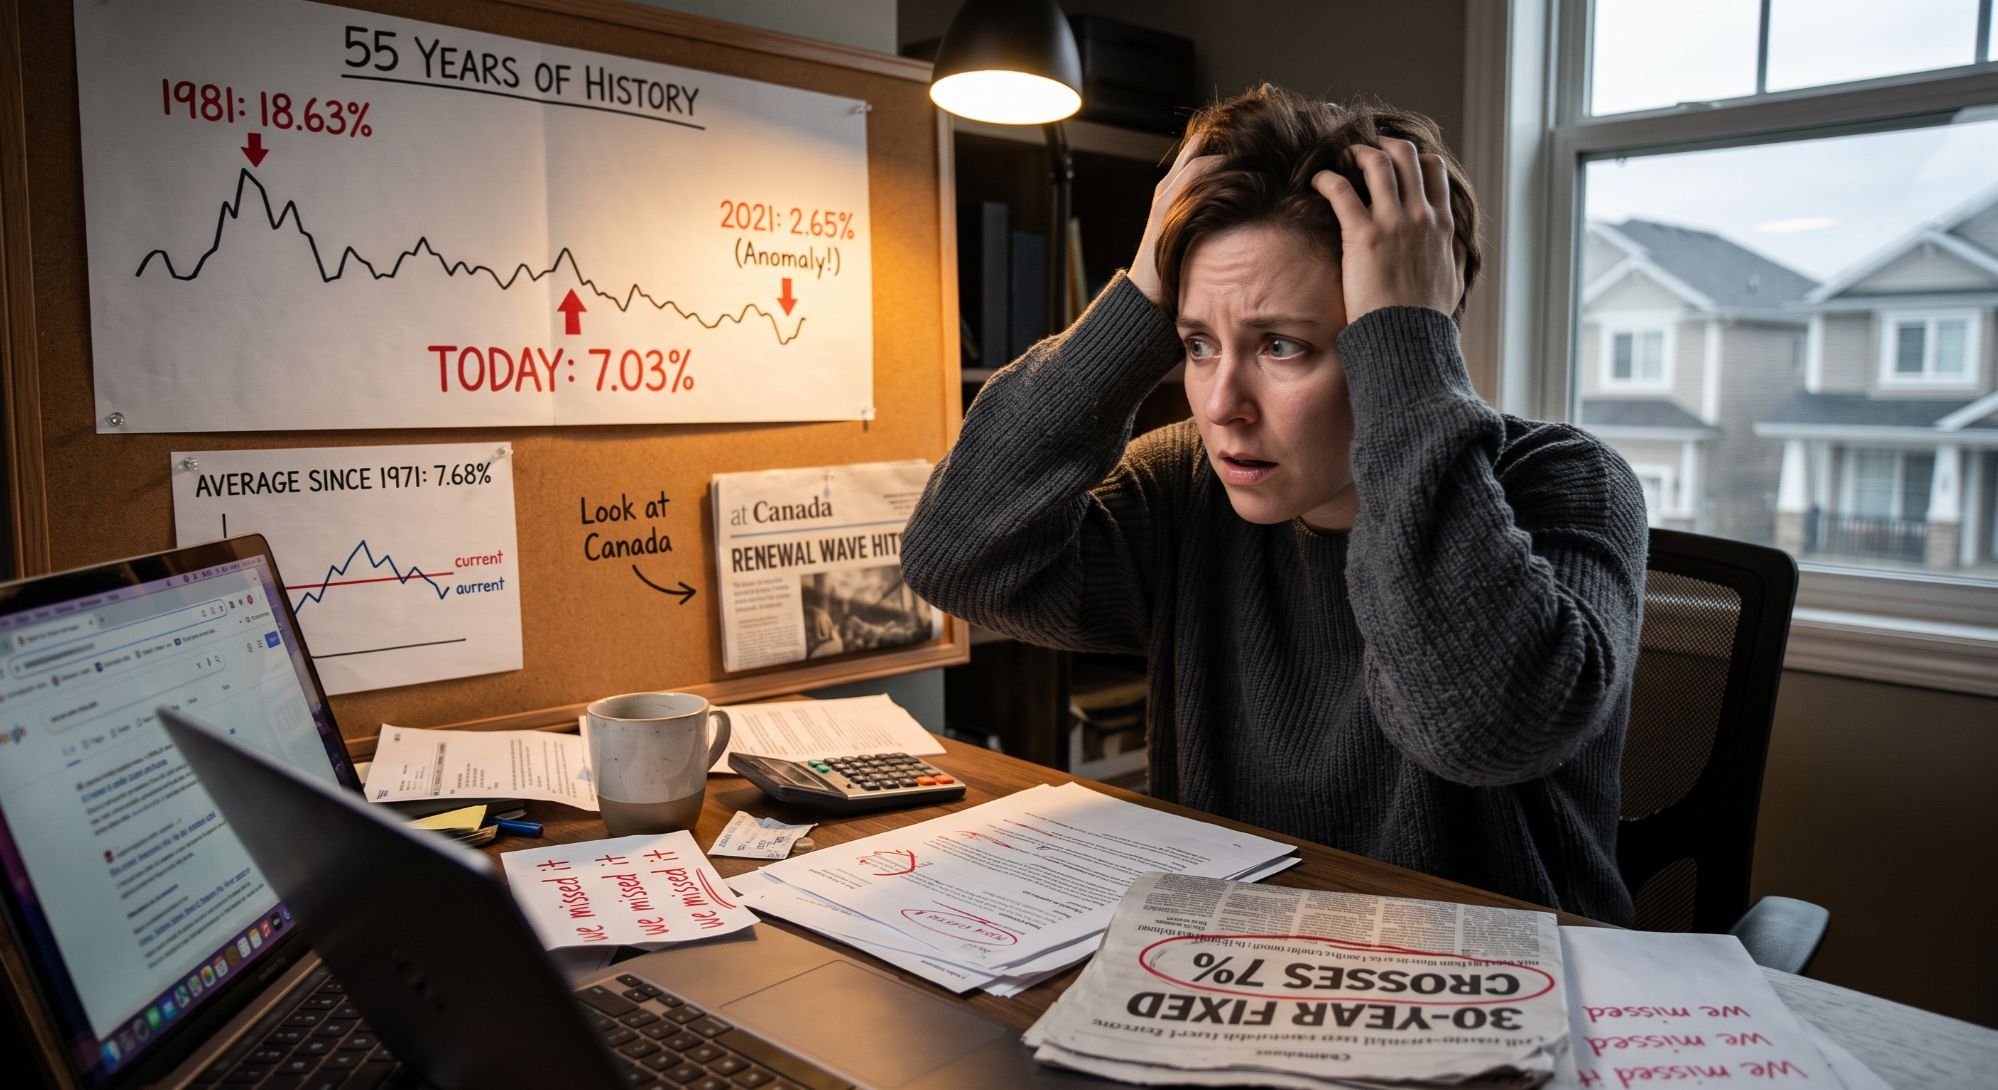
The average 30-year mortgage rate since 1971 is 7.68%. We are below it.
Start with the only number that matters for context
Freddie Mac has surveyed mortgage rates every week since April 1971. Across those fifty-five years — 666 monthly observations — the average 30-year fixed mortgage rate is 7.68%. The median is 7.19%.
We are at 7.03%. We are below both.
More than half of all months in the history of the survey — 53.5% of them — had a rate at or above where we are right now. Today sits at roughly the 46th percentile. Not at the edge of the distribution. In the middle of it.
And here's the part that tends to stop people: from April 1971 through August 1993 — 269 consecutive months, twenty-two and a half years — the 30-year fixed never once averaged below 7%. An entire generation of Americans bought homes, raised families in them, sold them, and built the majority of their net worth in them without ever seeing a 6% mortgage. Not once. Not for a single month.
Look at the decade averages and the picture gets clearer:
| Decade | Average |
|---|---|
| 1970s | 8.90% |
| 1980s | 12.70% |
| 1990s | 8.12% |
| 2000s | 6.29% |
| 2010s | 4.09% |
| Today | 7.03% |
One of those is not like the others. The 2010s were the anomaly, not the norm — and that decade is the entire frame of reference for most people buying homes today, and for a lot of the agents advising them.
Why money got that cheap — and it isn't a happy reason
This is the part almost nobody thinks through.
The two cheapest mortgage eras in American history were both emergency responses.
The 3.66% average of 2012 came out of the worst financial crisis since the Great Depression. The all-time record low — 2.65%, the week of January 7, 2021 — came out of a global pandemic. Rates like that are not a healthy economy rewarding patient buyers. They are a central bank holding the economy up with both hands because the alternative was worse.
Rate increases are the opposite tool, used on the opposite problem. They exist to bring inflation down. The Fed said so in plain language on September 16:
"Inflation remains elevated. Today's policy action will support a timelier return to the Committee's 2 percent goal."
Paul Volcker did the same thing in 1981, far more violently, and it worked — at the cost of the highest mortgage rates ever recorded, 18.63% the week of October 9 that year.
So when someone tells me they want 2021 rates back, I ask — gently — what else from 2021 they'd like back with them.
A market that can carry a 7% mortgage is a market that doesn't need rescuing. That is, on the whole, good news.
"But won't prices fall?"
This is the most reasonable-sounding question in real estate, and the historical record answers it in a way most people find genuinely surprising.
When mortgage rates hit 18%, home prices went up.
The national median price of an existing single-family home rose from $55,700 in 1979 to $75,500 in 1985 — a 35.5% increase — straight through the highest mortgage rates in American history. Not one down year. And the mirror image: the only sustained price decline in the entire record, 2007 through 2011, happened while rates were falling from about 6.4% to 4.5%.
The honest conclusion: rates move how many houses sell. They don't reliably move what houses sell for. Sales volume in 1981 was brutal — existing-home sales fell roughly 50% from their 1978 peak. But prices didn't break, because high rates suppress the number of buyers and the number of sellers at roughly the same time. That is exactly what we're seeing now: slower transaction volume, tight inventory, prices holding.
One asterisk I won't skip, because it matters: inflation ran about 42% from 1979 to 1985, so that 35.5% nominal gain was roughly flat in real, purchasing-power terms. Nobody who bought and held lost nominal equity. Nobody got rich in purchasing power either.
Affordability today is not 1981. It isn't close.
Rates alone are a bad measure of whether people can buy homes. The fairer measure combines rates, prices and incomes — that's what the National Association of REALTORS® Housing Affordability Index does, where 100 means the median family earns exactly the income needed to qualify for the median-priced home.
In 1981 that index bottomed at 68.9. The median American family earned only 69% of what it needed. Recent readings run 96.9 in 2023, 98.0 in 2024, and 104.7 as of August 2026 — essentially break-even.
The U.S. homeownership rate in early 1981, with mortgage rates at 18.63%, was 65.6% — higher than the 65.3% we have today. Meanwhile the all-time low homeownership rate, 62.9%, was recorded in mid-2016, when money was about as cheap as it has ever been.
Cheap financing and access to ownership are not the same thing. They sometimes move in opposite directions, because cheap money also bids prices up.
You can change the rate. You can't rebuy the house.
The phrase is worn out but the arithmetic behind it holds up.
From the October 2023 peak of 7.79%, mortgage rates were below 7% within two months, below 6.5% within eleven, and reached 5.98% in February of this year — a 1.81-point drop in 28 months, worth about 17% off a monthly payment.
The 1981 buyer waited longer. It took 49 months to see 11.78% and 54 months to get into single digits. But when relief came, it was the largest in history: going from 18.45% to 9.94% cut the payment on a $300,000 loan by 43%.
Every buyer who has ever purchased at a rate peak has eventually been able to refinance. Nobody gets to go back and buy the house at the old price.
So you think we have it bad: look at Canada
When the math starts feeling impossible, it helps to see how it works two hours north by plane.
There is no 30-year fixed mortgage in Canada.
A Canadian mortgage has a term — most commonly five years — entirely separate from its amortization, typically 25 years. At the end of every term the borrower renews at whatever rates exist that day. Whether they move or not. Forever. A Canadian buying this week isn't locking a rate until 2056. They're locking it until roughly 2031, and then finding out.
| United States | Canada | |
|---|---|---|
| Standard product | 30-year fixed | 5-year term / 25-year amortization |
| How often you re-price | Never, if you don't want to | About every five years, forever |
| Qualifying test | Debt-to-income | Contract rate +2%, or 5.25% — whichever is higher |
| Rate lock-in effect | Strong — it's why our inventory is tight | None. Nobody is trapped by an old rate |
| Central bank policy rate | 3.75–4.00% | 2.25% |
And they're living through the renewal wave right now
- Roughly 60% of every outstanding Canadian mortgage renews across 2025 and 2026 — not by choice, by contract.
- The Bank of Canada estimates that pandemic-era borrowers renewing in 2026–27, about 12% of all outstanding mortgages, face an average payment increase near 15%. Those are households that signed at 2% and are now signing at market.
- Canadian buyers must qualify at their contract rate plus two full percentage points — imagine telling a Tampa buyer at 7% that their lender will underwrite them at 9%.
Canada is not collapsing. Mortgages 60 or more days in arrears sit around 1.3% — slightly above the 2018–19 average and nothing resembling a crisis. Canadian households absorbed a re-pricing that would be unthinkable here, and their market kept functioning.
The American 30-year fixed is a genuine privilege rather than a birthright — it exists because of a secondary mortgage market most of the world never built, and it lets you freeze a payment for three decades while your income rises around it. If Canadians can re-price their entire housing debt every five years and keep buying homes, you can buy one at 7% and refinance when it suits you.
What I'd actually do
Nothing in the data above says this is an easy market. Volume is genuinely slow — existing-home sales are running near four million a year. But that's worth context too: the 1969–2001 average was about 3.3 million a year, and the 7.07 million of 2005 stands alone in fifty-five years of record. It was the anomaly, not the baseline.
What the data does say is that the story people are telling themselves — rates are historically high, prices are about to fall, we should wait — is not supported by fifty-five years of evidence. Rates are below the long-run average. Prices rose through 18%. The one true crash came while rates were falling. Affordability is closer to break-even than it was in 1981 by a wide margin.
If you're buying: get a real rate quote from a lender you trust, not a headline. Ask that lender what a refinance would actually cost you later, so you know the price of your own patience. And decide based on whether the house and the payment work for your life, because the rate is the one variable in the transaction you can change later.
If you're selling: price for the market you're in. Inventory is tight because most owners are locked into old mortgages and aren't moving — that supports your value, and it's also why serious buyers this fall are serious.
And if you're waiting for 2021 to come back, understand what you're actually waiting for.
Coming next
There is a second number that moves a Florida payment as much as the rate does, and it is on your ballot on November 3. Amendment 3 — what it changes, what it pointedly does not change, and what it is worth in dollars — gets a post of its own.
Aaron Bond is Broker at Engel & Völkers Tampa Downtown and a 2026 Florida Realtors Director for District 6. Rate figures are from Freddie Mac's Primary Mortgage Market Survey; historical rate, price, affordability and homeownership data from the Federal Reserve, FRED, HUD, the U.S. Census Bureau and the National Association of REALTORS®; Canadian data from the Bank of Canada and the Canadian Real Estate Association. This is market commentary, not legal, tax or investment advice, and it is not a rate quote — for current pricing, talk to a licensed lender.
Categories
Recent Posts